Prop Firm Risk Rules Explained: What Every Trader Should Understand
A prop firm evaluation is not simply a test of whether you can reach a profit target. It is also a test of whether you can manage losses within a specific set of rules. Traders can reach their profit objective and still fail because they misunderstand a daily loss calculation, allow floating losses to cross a drawdown threshold, or overlook a restriction on their trading strategy.
The challenge is that not all prop firms measure risk in the same way. Some use static maximum-loss limits, while others use trailing drawdown that moves as an account becomes more profitable. Some calculate limits using end-of-day values; others monitor account equity in real time. Futures programs can also use contract limits and liquidation rules that differ from those found in CFD evaluations.
This guide explains the main risk rules, compares eight prop firms, and shows how to evaluate a program before paying for a challenge.
Eight prop firms compared by risk-management rules
The ranking below combines CFD evaluation providers and futures-focused firms. It compares their published approaches to risk rather than suggesting that one model is universally safer. Rules can differ between account types at the same company.
| # | Prop Firm | Best For | Main Risk Model | Key Rule to Investigate | Editorial Rating |
|---|---|---|---|---|---|
| 1 | FTMO | CFD traders comparing structured evaluations | Daily loss plus maximum-loss rules that can trail | Daily reset, equity monitoring, and the selected challenge’s drawdown method | 4.8/5 |
| 2 | Topstep | Futures traders who need to understand a trailing loss floor | Trailing Maximum Loss Limit | How the limit moves as the account grows and how open P&L is treated | 4.7/5 |
| 3 | Leofins | Multi-asset CFD traders who prefer a static overall loss limit | Static maximum loss with a separate daily limit | Program-specific percentages, server-time reset, and prohibited strategies | 4.6/5 |
| 4 | The5ers | Traders comparing forex-oriented evaluation programs | Daily drawdown plus an overall loss limit | The daily reference value and the conditions of the selected program | 4.5/5 |
| 5 | FundedNext | Traders comparing multiple CFD challenge models | Static or trailing limits depending on the model | Daily-loss percentage, maximum loss, and minimum trading days | 4.4/5 |
| 6 | FundingPips | Traders choosing between different CFD evaluation structures | Model-dependent daily and overall limits | The exact model’s risk percentages and post-evaluation rules | 4.3/5 |
| 7 | TradeDay | Futures traders comparing end-of-day and intraday drawdown | EOD or intraday trailing drawdown, depending on the evaluation | When the limit is calculated and how a breach is enforced | 4.2/5 |
| 8 | MyFundedFutures | Futures traders comparing trailing drawdown and daily-loss arrangements | Plan-dependent EOD or intraday drawdown | Evaluation plan, soft-pause limits, contract caps, and funded-stage rules | 4.1/5 |
Editorial ratings are comparative judgments for this article, not verified payout probabilities or guarantees of trading success.
1. FTMO: Understand both daily loss and maximum loss
FTMO publishes detailed trading objectives, but traders should pay attention to the precise account type they intend to purchase. The daily-loss and maximum-loss calculations are separate controls, and a trader must remain within both.
Its published objectives describe a maximum daily loss calculated using the balance recorded at the daily reset and a specified loss allowance. Equity—including floating profit and loss and applicable trading costs—must remain above the resulting limit. FTMO also describes a maximum-loss rule that can trail upward as closed-trade balance reaches new highs.
The practical lesson is that a profitable closed balance does not necessarily mean that an account is safe. Open positions can still push equity below a permitted threshold.
What traders should check
- The daily-loss allowance and the time at which it resets.
- Whether floating losses, commissions, and swaps count toward the threshold.
- Whether the overall maximum-loss limit is static or trailing for the selected product.
- Any consistency requirements that affect reward eligibility.
- Whether a reward withdrawal can affect the account’s remaining loss allowance.
Do not assume that every FTMO product uses identical objectives. Read the current rules for the exact challenge and account stage.
2. Topstep: Learn how the Maximum Loss Limit trails
Topstep focuses on futures trading and uses a Maximum Loss Limit (MLL) to establish the lowest permitted account value. Under its published rules, the limit rises as the end-of-day balance grows, but does not move down when the balance declines. Once the limit reaches the starting balance, it locks at that level.
Topstep’s published MLL amounts include $2,000 for a $50,000 Trading Combine, $3,000 for a $100,000 account, and $4,500 for a $150,000 account. These figures apply to the specified account types and should not be assumed to cover every stage or product.
Why a trailing limit changes your decisions
Suppose a $50,000 Trading Combine begins with an MLL of $48,000. If the account’s end-of-day balance rises to $50,500, the limit moves to $48,500. The account has made money, but the permitted loss floor has moved closer to the starting balance.
Topstep also states that unrealized P&L counts toward the MLL in real time. A position can therefore trigger liquidation when its floating loss reaches the limit, even if the trader expects the market to reverse.
Practical approach: Track the current MLL rather than relying on the account’s original label. Leave a buffer for slippage, commissions, and rapid price movements, particularly when trading volatile futures contracts.
3. Leofins: Static overall drawdown with separate daily limits
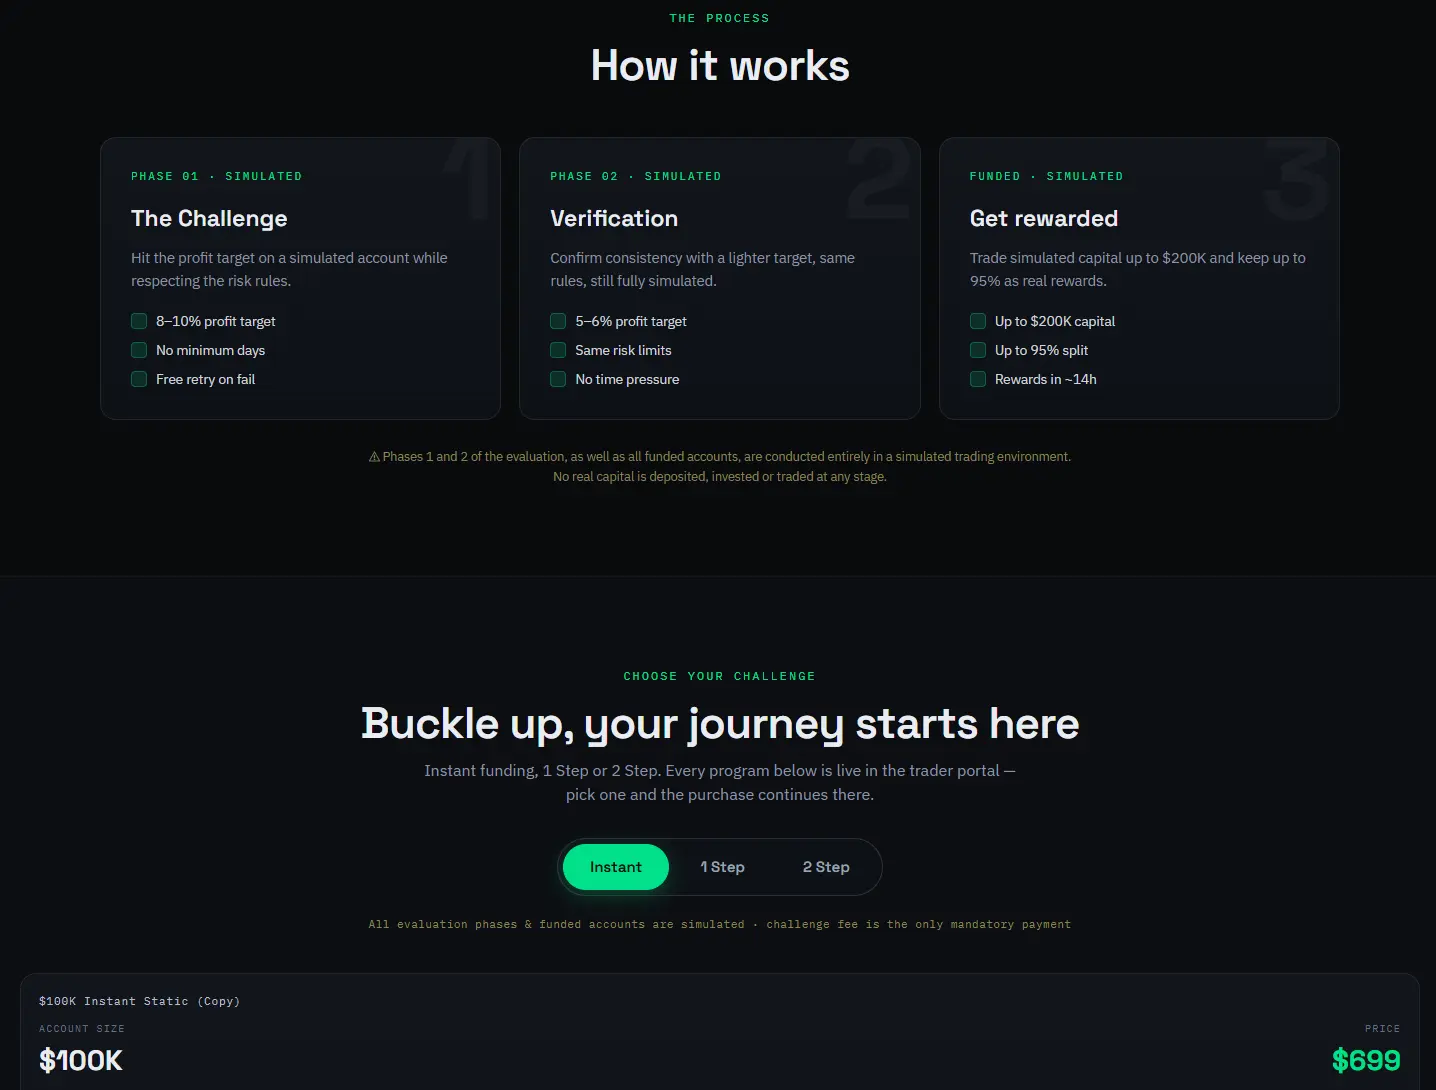 Leofins offers three principal CFD evaluation structures: Core 2-Step, Edge 1-Step, and Starter 3-Step. Its published rules describe a static maximum-loss threshold across these programs, meaning that the overall loss floor is tied to the initial balance rather than trailing upward as the account makes profits.
The official website, https://www.leofins.com/, provides the program details and current trading objectives.
How the limits differ
Leofins publishes the following risk limits for its three evaluation structures:
- Core 2-Step: 5% maximum daily loss and 10% maximum static loss.
- Edge 1-Step: 4% maximum daily loss and 7% maximum static loss.
- Starter 3-Step: 4% maximum daily loss and 8% maximum static loss.
These limits serve different purposes. The daily threshold restricts losses during the relevant trading day, while the static maximum-loss threshold establishes the overall floor from the initial account balance.
Leofins states that daily loss is calculated using the higher of the day’s starting balance or equity, with the limit resetting at midnight server time. Traders should confirm the exact current calculation and dashboard values for their selected program before beginning.
Why the distinction matters
A static overall limit is easier to map to a fixed starting reference because the floor does not move upward simply because the account reaches a new profit high. This can make the overall risk boundary more predictable than a trailing model.
However, static drawdown does not eliminate the daily limit. An account can breach its daily threshold long before reaching its overall floor. Floating losses and applicable trading costs must also be considered.
Leofins publishes no maximum evaluation duration, with a minimum of two trading days per phase. Its rules also allow news trading and weekend holding subject to a stated 1% risk limit, permit personal trader-controlled expert advisors, and prohibit practices such as latency arbitrage and tick scalping. Hedging is permitted within one account but not across separate accounts. These permissions and restrictions should be verified against the latest rules.
Practical approach: Convert both the daily limit and the overall static loss threshold into account-currency amounts. Then set personal trade-risk limits well below the firm’s hard boundaries. A predictable overall floor is useful only if the strategy also respects the daily restriction and all other program rules.
4. The5ers: Check the daily reference value
The5ers offers several evaluation programs, so the relevant risk model depends on the selected product. Its published High Stakes rules describe a 10% maximum loss from the initial balance and a 5% daily drawdown based on the higher of the previous day’s closing equity or balance.
Its published 2-Step plan specifications describe a different daily-loss percentage: 3% of the previous day’s closing balance or equity, whichever is higher, with a 10% maximum loss from the initial balance. This is a useful example of why traders should not apply one program’s rules to every account offered by a firm.
What the daily reference means
If the previous day’s closing equity is higher than its balance, that equity value may be used to calculate the next daily threshold. A profitable day can therefore raise the reference used for the following day’s daily-loss calculation.
This does not necessarily mean the overall loss floor is trailing. Daily drawdown and maximum loss are separate rules and should be calculated independently.
Practical approach: Identify the precise evaluation name, record the reset time, and calculate the daily threshold using the reference specified in that program’s documentation. Also check whether consistency requirements apply during the evaluation, after funding, or only when requesting a payout.
5. FundedNext: Risk limits vary by challenge model
FundedNext’s CFD rules show how much the risk structure can change between account models. Its published general rules list the following daily-loss and maximum-loss conditions:
- Stellar 1-Step: 3% daily loss and 6% static maximum loss.
- Stellar 2-Step: 5% daily loss and 10% static maximum loss.
- Stellar Lite: 4% daily loss and 8% static maximum loss.
- Stellar Instant: No daily loss limit under the published model, but a 6% trailing maximum-loss limit.
For the listed CFD models, the daily limit resets at 00:00 server time. FundedNext states that the daily-loss calculation includes realized and unrealized P&L, swaps, and commissions.
Why model selection comes first
A trader comparing Stellar 1-Step with Stellar 2-Step should not focus only on the number of evaluation phases. The first model has a tighter overall loss allowance, while the second allows a larger maximum loss under the published figures. The daily-loss percentages also differ.
The Instant model illustrates another trade-off: not having a daily loss limit does not mean the account has no risk boundary. A trailing maximum-loss rule can still be breached.
Practical approach: Compare the profit target, daily-loss allowance, maximum-loss method, minimum trading days, and post-evaluation rules together. A challenge with fewer stages is not automatically easier to pass.
6. FundingPips: Distinguish evaluation rules from Master Account rules
FundingPips offers several CFD models, including 1 Step Flex, 2 Step Standard, 2 Step Pro, 2 Step Flex, and Zero Instant Master. Its published comparison table assigns different risk limits to these options.
For example, the published 2 Step Standard model lists an 8% profit target in Phase 1 and 5% in Phase 2, a 5% maximum daily loss, and a 10% static maximum overall loss. Other models have different combinations, including a 6% static overall limit for 2 Step Pro and a trailing overall limit for Zero Instant Master.
FundingPips also distinguishes between the evaluation and Master Account stages. A rule that applies during evaluation may not be the only condition that matters once the account qualifies for rewards.
What to check before paying
- The daily-loss percentage for the exact model.
- Whether the overall limit is static or trailing.
- The profit target and minimum trading days for each phase.
- Any maximum open-risk or consistency requirements.
- News-trading restrictions after the evaluation.
- Reward request intervals and eligibility conditions.
FundingPips is best assessed by reading the selected model’s full rule set rather than relying on a generic summary of the company. The product name is part of the risk calculation.
7. TradeDay: End-of-day and intraday drawdown are not interchangeable
TradeDay is a futures-focused provider whose published documentation describes different maximum-drawdown calculation methods, depending on the evaluation purchased.
An end-of-day (EOD) trailing limit is calculated from the end-of-day balance. An intraday trailing limit can respond to unrealized account values during the session. Although the reference may be calculated differently, TradeDay states that its limits are enforced in real time.
This distinction is particularly important for futures traders, whose positions can move quickly during scheduled economic releases or periods of thin liquidity.
A practical example
Suppose a trader has an open futures position that moves into a substantial floating loss. Under an intraday trailing rule, the account can touch the maximum-drawdown threshold before the trader closes the position. Under an EOD calculation, the reference used to set the threshold may be based on the end-of-day balance, but the firm can still enforce the resulting limit in real time.
The exact effect depends on the purchased evaluation and its current terms.
Practical approach: Before choosing TradeDay, identify whether the program uses EOD or intraday trailing drawdown. Check the starting floor, when the reference moves, and what happens when an open position touches the limit. Do not assume that an EOD calculation means the account can safely move below its current threshold during the session.
8. MyFundedFutures: Compare plan-specific drawdown and daily-loss rules
MyFundedFutures offers futures evaluation plans with different risk parameters, including Builder, Rapid, Rapid EOD, and Pro. Its published evaluation guidance distinguishes between end-of-day drawdown and intraday drawdown, and some plans use daily-loss limits that pause trading rather than immediately functioning like an overall maximum-loss rule.
For example, its published Builder specifications include EOD trailing maximum-loss limits and plan-specific daily-loss soft pauses. The maximum-loss amount varies with account size and whether an optional drawdown add-on is selected.
Other plans use different consistency requirements, minimum trading days, and contract limits. The rules can also differ between evaluation and simulated-funded stages.
Why a soft pause is different from a hard breach
A soft pause can stop trading for the day when a specified loss amount is reached. It is not the same as an overall maximum-loss threshold that terminates the evaluation if breached. Traders should understand both controls and how they interact.
Contract limits matter too. A futures account may permit only a specified number of mini or micro contracts, and increasing position size can make it easier to reach the loss threshold during a volatile move.
Practical approach: Compare the plan’s EOD or intraday drawdown, daily soft-pause amount, maximum contracts, consistency requirement, and rules for holding positions outside trading hours. Confirm which conditions continue to apply after the account advances beyond evaluation.
The risk rules every trader should understand
The details differ across providers, but six concepts deserve particular attention before you buy any challenge.
Daily loss limit
A daily loss limit caps how much the account can lose during a defined trading day. The firm’s calculation may use a starting balance, starting equity, or another specified reference.
The reset time is important. It may follow server time rather than your local time. Around daylight-saving changes, the difference between local time and the firm’s reset can shift.
Never assume that a new date on your computer automatically resets the firm’s daily-loss allowance.
Maximum loss and maximum drawdown
The overall loss threshold defines the account’s permitted decline from a reference value. A static limit remains tied to its specified starting reference, while a trailing limit can rise as the account reaches new highs.
A trailing rule may leave less room for later losses after a profitable period. That is why traders should track the current floor, not just the starting drawdown allowance.
Balance versus equity
Balance generally reflects completed trades and booked adjustments. Equity also includes floating P&L on open positions, along with costs included in the firm’s calculation.
If a firm monitors equity in real time, a position can breach the rule before it is closed. This can happen even if the trader believes the market may soon reverse.
Consistency requirements
Some firms restrict how much of the account’s total profit can come from a single day or impose other performance-distribution conditions. Depending on the program, failing a consistency requirement may delay reward eligibility rather than immediately terminate an account.
Read the wording carefully. Determine whether the rule affects evaluation completion, payout eligibility, or ongoing account access.
Position limits and correlated exposure
A trade can remain within the loss limits when opened but still create excessive risk if the position size is too large for the market’s volatility.
Multiple correlated positions can compound the same exposure. For example, positions on two closely related equity indices may both lose when the same market event moves prices against the trader.
Calculate combined exposure rather than treating each position as an independent risk.
News, weekend, and automation restrictions
Some programs restrict trading around major economic releases, holding positions over weekends, hedging, copying trades, or using particular automated strategies. Other firms allow some of these activities under specific conditions.
A platform’s ability to execute a strategy does not mean the prop firm permits it. Check the current prohibited-strategy list before using a bot or an execution method that may fall into a restricted category.
How to calculate a personal risk buffer
The firm’s risk limits are hard boundaries, not a recommended amount to lose during normal trading. A personal risk plan should leave room for a losing streak, execution costs, and unexpected volatility.
Consider a hypothetical $100,000 account with a 5% daily loss allowance. If the rule is based on 5% of the initial balance, the nominal daily amount is $5,000. The actual threshold still depends on the firm’s reference value, reset time, and treatment of open P&L.
A trader might choose to risk $250 on a planned trade, equivalent to 0.25% of the initial account balance. Four full losses would total $1,000 before slippage, commissions, and other costs. This leaves more room than risking $1,000 per trade, but it does not guarantee compliance: several correlated positions or a fast market can increase losses unexpectedly.
Before placing a trade, calculate:
- The current daily-loss threshold in account currency.
- The current maximum-loss floor.
- How much room remains before either limit is reached.
- The planned risk on each position.
- The combined exposure of open and correlated positions.
- A buffer for slippage, commissions, swaps, and volatile conditions.
A stop-loss order can help control risk, but it does not guarantee an exact exit price in every market condition. Avoid using the entire permitted loss as your normal risk budget.
Common mistakes that lead to rule breaches
Monitoring only closed-trade results
A positive balance can hide a large floating loss. Track equity and the firm’s displayed risk metrics, not only completed trades.
Forgetting that a trailing limit moves
A profitable period may raise the drawdown floor. Recalculate the remaining allowance after new account highs instead of relying on the original amount.
Trading too close to the threshold
A small adverse move, spread expansion, or slippage can push an account over its limit. Leave a buffer rather than trying to use every dollar of permitted loss.
Misunderstanding the reset time
The daily-loss calculation may reset according to server time. Record the time and understand which value forms the next day’s reference.
Assuming all products use the same rules
A firm’s one-step challenge may differ from its two-step product. Evaluation rules may also change after the account advances. Review the terms whenever you select a new model or stage.
Treating the firm’s maximum as your target
A loss limit exists to prevent the account from exceeding a defined risk boundary. It is not a suggested amount to risk. Build your position sizing around a smaller personal threshold.
Frequently asked questions
Is a daily loss limit the same as maximum drawdown?
No. A daily loss limit applies to a defined trading day, while maximum drawdown or maximum loss governs the account’s broader permitted loss. Both can apply at the same time, and breaching either can have serious consequences.
Can floating losses breach a prop firm account?
Yes, if the applicable rule monitors equity or unrealized P&L. A position can trigger a breach before it is closed, even if the market later reverses.
Is static drawdown safer than trailing drawdown?
Neither is automatically safer. Static drawdown provides a fixed overall threshold, while trailing drawdown may rise as the account reaches new highs. The more suitable model depends on the strategy and how much room remains after profitable trading.
Do futures prop firms use the same risk rules as CFD firms?
Not necessarily. Futures programs may use contract limits, session-based liquidation, and end-of-day or intraday trailing drawdown. CFD programs may instead express daily and maximum loss as percentages of simulated capital. Compare the actual calculations rather than assuming the percentages are interchangeable.
Should I risk the full daily loss allowance?
No. The daily limit is a hard boundary, not a target. Using the entire allowance leaves little room for additional positions, slippage, or unexpected volatility.
Can I assume the rules remain unchanged after passing?
No. Some firms apply different conditions during evaluation and after the account advances. Review the rules for each stage, including payout eligibility and any consistency requirements.
Build your trading plan around the rules
Prop firm risk rules determine how much adverse movement an account can tolerate and what happens when a limit is reached. Understanding the percentages is only the first step; traders also need to know the reference values, reset times, and whether floating losses count.
FTMO demonstrates the importance of daily and overall loss calculations. Topstep highlights the effect of a trailing futures loss floor. Leofins offers a static overall loss model across its published CFD programs, while The5ers, FundedNext, FundingPips, TradeDay, and MyFundedFutures illustrate how much conditions can vary between products.
Before paying for a challenge, convert the limits into account-currency amounts, understand how equity is measured, and choose a position size that leaves a reasonable buffer. A well-matched program is one whose rules you can follow consistently—not one that simply advertises the largest account or the most generous headline percentage.
Prices and conditions are current as of October 2026.
Risk disclaimer: Proprietary trading evaluations involve financial risk. Challenge fees may be lost if an evaluation is unsuccessful or program rules are breached. Simulated trading and funded-program results do not guarantee future performance or income. Review the current terms carefully and never spend money you cannot afford to lose.